How interest rates reach your mortgage, your spending and your investments.
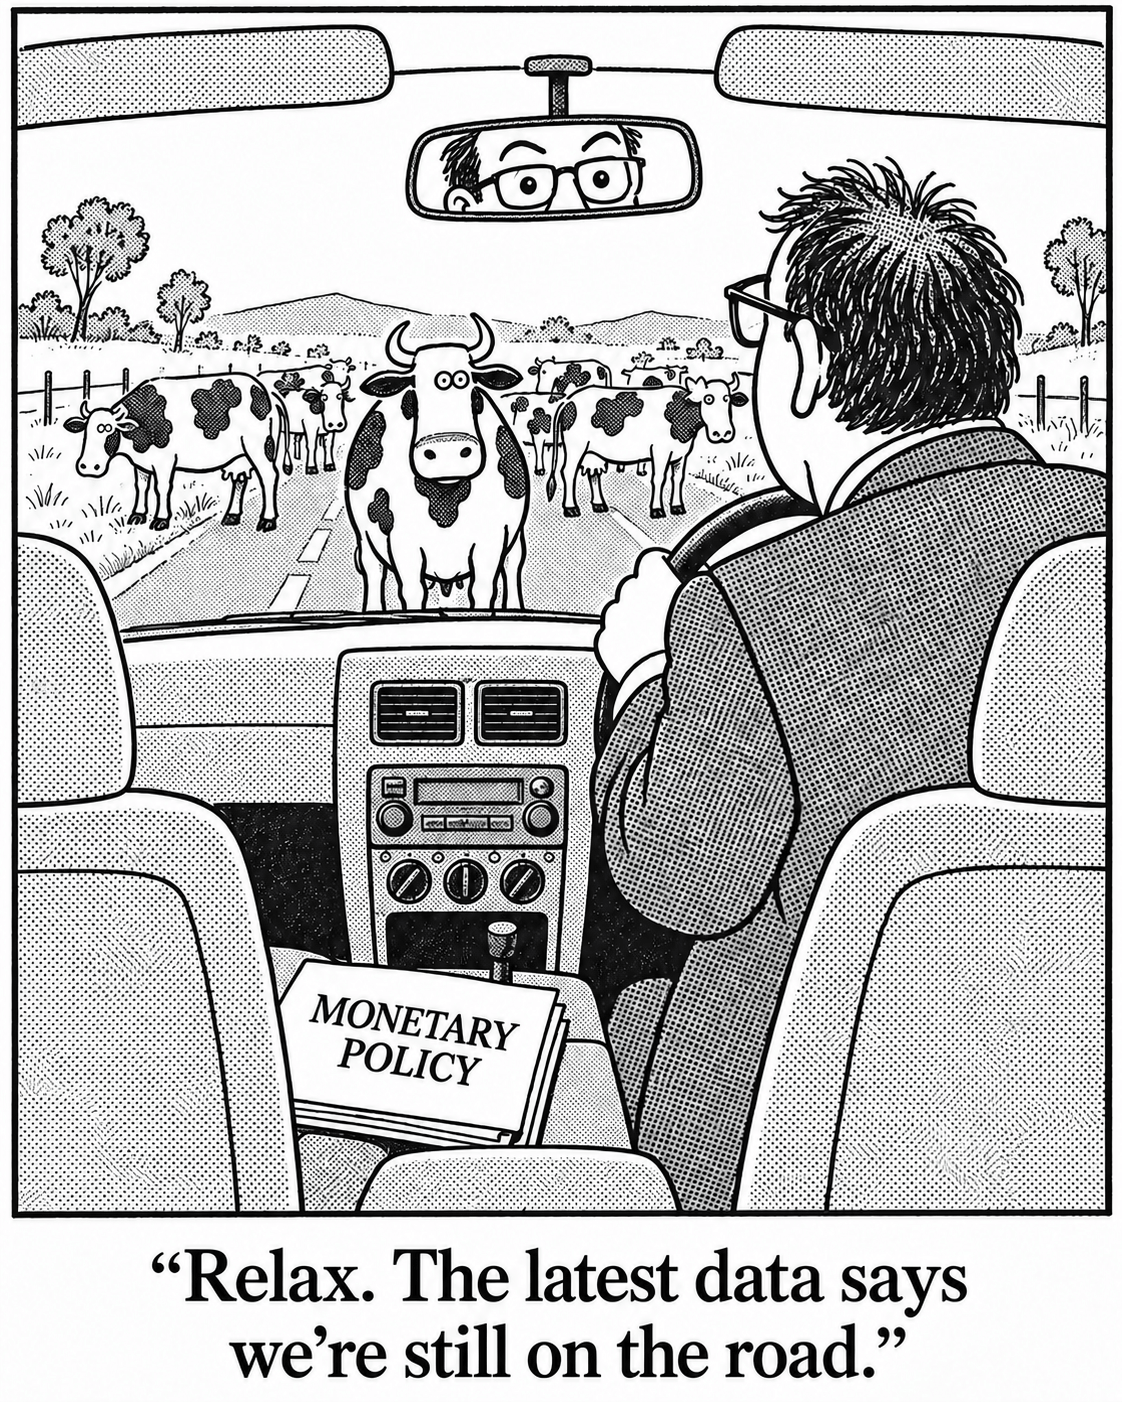
When I was studying accounting, an economics lecturer compared controlling inflation to driving a car while only being able to look in the rear-view mirror.
That image pops into my head whenever there’s a decision on interest rates. Every single time, without fail.
The announcement on 29 September was no different.
The RBA announced its fourth rate increase of 2026, taking the cash rate target to 4.60%, effective 30 September.
In the same statement, the Board said the economy appeared to be slowing. Earlier increases were having an effect, but fresh pressures were adding to inflation.
Disruptions to global oil supplies were pushing up energy costs, with higher fuel prices feeding into other goods and services. At home, demand was still putting pressure on what businesses could supply, while weak productivity growth limited how quickly the economy could expand. RBA decision statement.
For the people affected, the announcement meant different things.
A household facing another increase in mortgage repayments. A business owner reconsidering an expansion. Someone relying on interest from savings who would rather rates stayed higher.
They still meet at the same supermarket checkout, though.
There’s no cash rate that makes everyone happy. The RBA pursues price stability and full employment, using a flexible inflation target of 2% to 3%. It must judge how much restraint the economy needs, knowing the effects take time to arrive. RBA monetary-policy framework.
The Board has forecasts and timely information, so my lecturer’s analogy has its limits. But the difficulty of making a decision before the picture is complete still holds.
How higher rates slow spending
Consider a business owner planning to buy a second delivery van.
The van should generate income. Financing it creates a cost. When borrowing becomes more expensive, the owner may decide to wait.
Similar decisions happen across the economy. Renovations get postponed. Businesses scale back expansion. Mortgage payments leave households with less to spend. Saving becomes more attractive.
The RBA influences this through its target for the cash rate: the interest rate on unsecured overnight loans between banks. That feeds into borrowing and deposit rates throughout the economy.
Higher rates generally restrain demand relative to what would otherwise have happened, helping reduce inflationary pressure. But the effect depends on how households and businesses respond. RBA transmission explainer.
For some borrowers, the response starts with their next repayment. Others might barely notice until a contract expires.
Your mortgage has its own calendar
Between December 2023 and January 2025, the cash rate target stayed at 4.35%.
Yet the average interest rate on outstanding owner-occupier mortgages rose from approximately 5.9% to 6.2%. RBA lending data.
The expiry of cheaper fixed-rate loans helps explain why.
A borrower could sit through several RBA increases with unchanged repayments, then face a substantial jump when their fixed term ended, even while the RBA was holding rates steady.
Refinancing, competition and the changing mix of loans also influenced the average. But earlier decisions were still reaching households. RBA mortgage-rate analysis.
A pause in rate increases doesn’t mean their effects have finished arriving.
Inflation fell. The shopping bill didn’t.
Australia’s annual-average inflation rate declined from approximately 6.6% in 2022 to about 3% in 2025.
Yet average consumer prices in 2025 were about 24% higher than in 2019. A representative collection of goods and services costing $100 in 2019 would therefore cost roughly $124 in 2025. RBA/ABS CPI data.
Your particular expenses may have changed differently. But the distinction is straightforward:
Lower inflation doesn’t return the basket to $100.
Prices are still rising, just more slowly.
Those prices also influence what we expect next. Research using US household data found that frequently encountered grocery-price changes helped shape people’s inflation expectations. D’Acunto and colleagues.
A familiar price tag gives you a concrete comparison. A national statistic covers millions of purchases you never make.
An improving inflation figure and a frustrating supermarket visit can both be telling you something true.
Why cheaper borrowing doesn’t guarantee rising shares
Markets have another calendar again. Investors can adjust prices before a rate decision, based on what they expect to happen.
And interest rates arrive alongside other information about the economy and company earnings.
Between the end of August and December 2008, the RBA cut the cash rate from 7.25% to 4.25%. Over the same period, the ASX 200 fell approximately 27.5%, excluding dividends.
The RBA was responding to deteriorating economic conditions during the global financial crisis. Its December statement described fragile market sentiment, weakening demand and more cautious households and businesses. RBA December 2008 statement.
Cheaper borrowing can support businesses and valuations while a worsening outlook for profits pushes in the opposite direction.
That fall doesn’t show that the cuts caused the losses, or that the cuts had no effect. We don’t observe what the market would have done without them.
Growth can continue while rates are working
Return to the business owner who postponed the second van.
The business might still grow using the vehicle it already has. Higher rates have changed the expansion plans without necessarily stopping growth altogether.
Across the economy, that distinction matters. Spending can keep increasing even while monetary policy restrains it relative to what would otherwise have happened.
Likewise, persistent inflation doesn’t, by itself, prove rate increases failed. Falling inflation doesn’t prove the RBA deserves all the credit. Energy prices, supply conditions and other forces matter too.
September’s decision brought those overlapping effects into view: slowing demand alongside renewed inflation pressure.
The Board had to judge how much restraint was already working through the economy and whether more was needed. Households and businesses will experience that decision through repayments, interest income, purchases and hiring plans over the months ahead.
Every rate announcement takes me back to that classroom. The longer I follow these decisions, the more I appreciate what the lecturer was getting at.
Data note: The ASX 200 change is calculated using EODHD index closing values from the end of August to the end of December 2008 and excludes dividends. Cash-rate and mortgage figures use RBA data. Consumer-price comparisons use calendar-year averages. Historical examples illustrate economic mechanisms; they do not isolate the causal effect of monetary policy.
General information for educational purposes. This article does not recommend buying or selling investments.